Business Insurance Explained: Everything Every Business Owner Should Know
Business Insurance is a group of policies that help an organisation manage financial losses from unexpected events. A business may face damage to its premises, theft of stock, legal claims, employee injuries, data breaches, or interruptions to daily operations.
Insurance developed as a way to share certain risks across many policyholders rather than leaving one organisation to carry every covered loss alone.
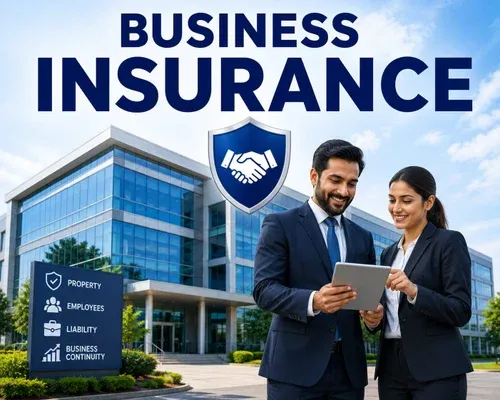
Indian businesses range from small shops to manufacturers, technology firms, and transport companies. Their risks differ by activity, location, workforce, assets, and customers. Business Insurance is not one standard policy; it combines covers suited to an organisation's circumstances.
Common Types of Business Insurance
Property insurance may protect buildings, machinery, furniture, and stock against specified events such as fire or certain natural disasters. Public liability insurance can cover legal liability for injury to another person or damage to their property arising from business activities.
Professional indemnity insurance addresses certain claims alleging negligence, errors, or omissions in professional work. Product liability relates to injury or damage allegedly caused by a product. Cyber insurance may help with eligible losses linked to data breaches, attacks, recovery, and related legal responsibilities.
Other policies cover goods in transit, employee injuries, or interruption after insured physical damage. Policy wording sets out limits, exclusions, and conditions.
Importance
An incident can affect more than a company's physical assets. A fire may damage stock and stop operations, a customer injury may lead to a legal claim, and a cyber incident may disrupt systems or expose confidential information.
Such events affect owners, employees, customers, suppliers, and business partners. Smaller organisations may have limited reserves and depend on a few premises, vehicles, or key people. A suitable policy can help manage covered losses and support continuity planning.
Risks That Business Owners May Need to Consider
Risks depend on the activity. A shop may focus on fire, theft, customer injury, and stock damage. A factory may also consider machinery breakdown and employee injury. A consultancy may focus on professional liability, cyber incidents, and confidential records.
A risk review can consider:
Physical assets: Buildings, equipment, furniture, inventory, and fixtures.
People: Employee injury obligations and group health or accident arrangements.
Third-party exposure: Claims involving customers, visitors, suppliers, or the public.
Digital exposure: Customer information, payment systems, networks, and stored records.
Operational continuity: The effect of a temporary closure or supplier disruption.
Insurance does not remove the underlying risk. Safety procedures, staff training, secure systems, maintenance, and emergency planning remain important.
Recent Updates
Between 2024 and 2026, India's insurance framework saw changes related to product governance and policyholder protection. They do not create one compulsory package for every business.
Regulatory and Market Developments
In 2024, the Insurance Regulatory and Development Authority of India (IRDAI) introduced updated regulations for insurance products and policyholder protection. The framework focuses on product oversight, clear policy information, and complaint handling.
In December 2025, Parliament passed the Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Bill. It raised the permitted foreign investment limit in Indian insurance companies to 100 per cent and provided for a Policyholders' Education and Protection Fund.
During 2026, IRDAI advanced related rules on policyholder education, grievance redressal, and accountability in insurance distribution. For businesses, organised policy documents, proposal details, and written correspondence remain important.
Laws or Policies
Indian law does not require every company to hold one general business policy. Specific activities can create insurance or employee-protection obligations, depending on the workforce, vehicles, materials, and location.
Important Legal Requirements
Under the Motor Vehicles Act, 1988, a motor vehicle used in a public place must have third-party insurance. This applies to commercial vehicles as well as private vehicles. Vehicles carrying or intended to carry hazardous goods may have additional requirements under the Public Liability Insurance Act, 1991.
That Act requires owners handling specified hazardous substances to take out insurance before beginning the activity. Its purpose is to provide relief to people affected by certain accidents involving those substances.
The Employees' Compensation Act, 1923 sets out employer liability for specified work-related injury, disablement, or death. An employer may use insurance to fund eligible liabilities, but the legal duty and policy are separate. The Employees' State Insurance scheme also applies to covered establishments and eligible employees.
Understanding Policy Conditions
A policy should be checked for its insured amount, covered events, exclusions, deductibles, geographical limits, claim notification rules, and renewal terms. A property policy may not automatically include flood damage, machinery breakdown, or interruption losses; these may require separate extensions.
The business name, address, activity, asset values, and employee information should be accurate. Changes such as a new location or manufacturing activity may need to be reported to the insurer.
Tools and Resources
Practical records help businesses identify risks and organise insurance details. An asset register can list buildings, equipment, stock, and replacement estimates. A checklist can record fire protection, data security, transport, and workplace safety.
| Resource | How it may help |
|---|---|
| Asset register | Records property, equipment, and stock |
| Risk checklist | Identifies business-specific exposures |
| Continuity plan | Records steps for disruption and recovery |
| Policy comparison sheet | Tracks limits, exclusions, deductibles, and renewals |
| IRDAI Bima Bharosa | Registers and tracks insurance complaints |
IRDAI's Bima Bharosa platform allows policyholders to register and monitor complaints. Policy documents, proposal forms, and claim forms are useful references when reviewing cover.
FAQs
What does Business Insurance cover?
It may cover property damage, third-party liability, employee-related risks, professional mistakes, cyber incidents, or business interruption. Exact protection depends on the policy wording.
Is Business Insurance mandatory in India?
There is no single rule requiring every business to hold a general policy. Specific requirements apply to certain vehicles, hazardous activities, and employment situations.
Which type of Business Insurance does a small business need?
It depends on the activity, assets, premises, staff, and digital systems. A risk review can identify relevant policy categories and gaps.
Does Business Insurance cover business interruption?
Some policies include interruption cover or make it available as an extension. It may depend on specified insured damage and include a waiting period, an indemnity period, and exclusions.
How are Business Insurance claims assessed?
The insurer reviews the policy, event, evidence, limits, and conditions. Invoices, photographs, repair estimates, and incident reports may be required.
Conclusion
Business Insurance helps organisations manage selected risks involving property, liability, employees, cyber incidents, and operational disruption. The relevant policies vary with business activities and legal responsibilities. Indian law sets specific requirements for certain vehicles, hazardous activities, and employment situations, while other covers depend on the organisation's circumstances and policy wording.